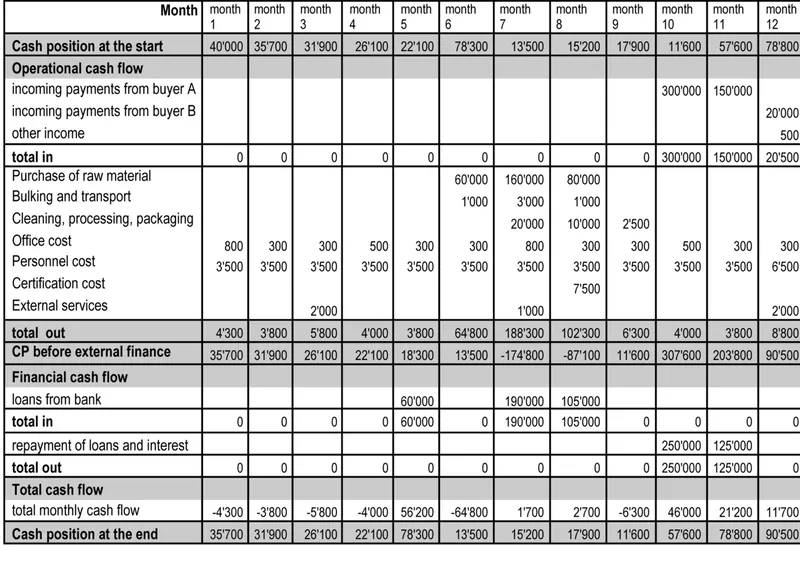
Big life changes rarely hit just one side of the budget. A new baby can cut income during leave and raise costs in the same month. Starting a business can drop your pay to zero while setup costs arrive. The fix is the same each time: map the months around the event, find the gap, and fund it before it starts.
The Four-Step Method
- Write down the timeline. When does income change, and for how long? When do new costs start, and are they one-off or ongoing?
- Build a month-by-month table for the six months before and after the event, with expected income, normal costs and event costs.
- Find the gap. Add up every month where costs exceed income. That total is the cash you need set aside.
- Fund the gap in advance with a dedicated savings account and an automatic monthly transfer.
Worked Example: Parental Leave
A household takes home $6,000 a month and spends $5,200. One parent plans 12 weeks of leave, three months with $2,000 less take-home pay each month. Baby-related costs add about $400 a month once the baby arrives, plus $1,500 in one-off purchases.
| Month | Income | Spending | Gap |
|---|---|---|---|
| Leave month 1 | $4,000 | $7,100 | −$3,100 |
| Leave month 2 | $4,000 | $5,600 | −$1,600 |
| Leave month 3 | $4,000 | $5,600 | −$1,600 |
| Back to work | $6,000 | $5,600 | +$400 |
The three leave months need $6,300 set aside. Saving $800 a month (their normal surplus) for eight months covers it before the baby arrives. Notice the surplus also shrinks for good, from $800 to $400, once the new monthly costs start. Plan the next budget around that.
What to Plan For, by Event
A new baby
Check what your employer pays during leave and whether your state has paid family leave. The U.S. Department of Labor explains unpaid, job-protected leave under the Family and Medical Leave Act, including who qualifies. Review your health plan's deductible and out-of-pocket maximum, since a birth often reaches it. Childcare is frequently the largest new cost, so get local quotes early.
A move
Costs come in a cluster: deposits, movers, overlapping rent or mortgage for a month, utility setup, and household items. If you're moving for a job, ask whether relocation costs are covered. Budget for a different cost of living, not just the move itself.
A job change or layoff
Plan for a gap between the last paycheck and the first new one, which can be several weeks even with a job lined up. Check when health coverage ends and what continuing it will cost. If you're laid off, apply for unemployment benefits promptly, since there's usually a waiting period. An emergency fund sized to your fixed costs is what carries you through.
Starting a business
Count personal living costs and business setup costs separately. Many new businesses take months to pay the owner anything. A common approach is to save enough personal runway to cover your living costs for that stretch, separate from the business's startup funds. Once revenue arrives, pay yourself a fixed amount instead of drawing whatever is in the account.
Divorce or separation
One household becomes two, and fixed costs nearly double while income splits. Get legal advice on support and asset division before making major financial changes, and build a new budget for a single income as early as you can.
Keep It Separate From Your Emergency Fund
A planned event isn't an emergency. Saving for it in its own account, like a sinking fund, keeps your emergency fund whole for the things you can't plan, which tend to show up during big transitions.
Revisit After the Event
Most life events leave a permanent change: a new childcare bill, a higher rent, a different pay schedule. Three months after the event, rebuild your budget from real numbers. Short- and long-term cash flow goals may need new deadlines once the dust settles.
Frequently Asked Questions
How far ahead should I start saving for a life event?
As soon as you know it's coming. Divide the gap by the months you have. If the monthly amount is too high, look at which costs can wait until after the event.
Should I pause retirement contributions during a big life event?
It's an option for a short, defined gap, but try to keep contributing enough to get any employer match, since that money is hard to make up. Restart full contributions as soon as income returns.
What if the event is sudden, like a layoff?
Cut to essential spending right away, apply for any benefits you qualify for, and use your emergency fund for the gap. Then contact lenders early if you expect to miss a payment; many have hardship options.