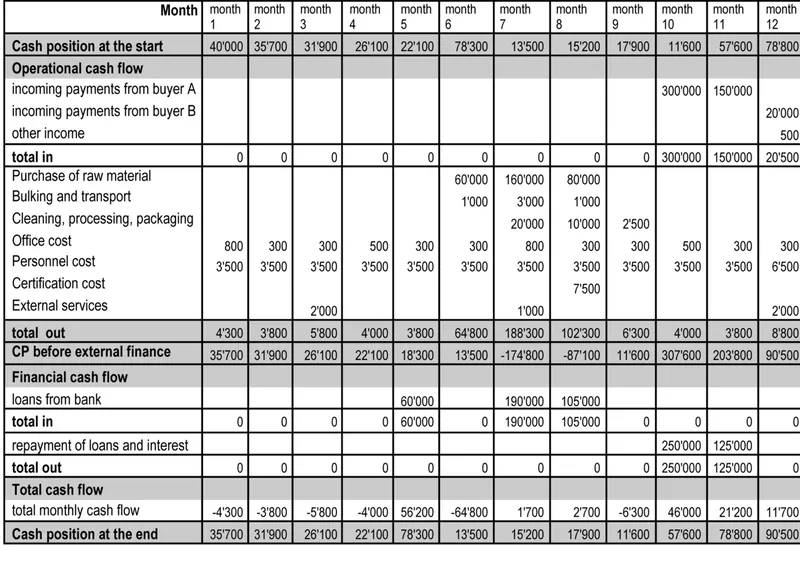
AI cash flow forecasting uses machine learning to predict your future bank balance from your past transactions. The software learns which payments repeat, when each customer really pays, and how your cash moves through the year, then projects those patterns forward by day or week. It's useful when you have at least a year of clean transaction history and enough volume for patterns to show. It won't know about the new contract you signed yesterday, so the best forecasts combine the model's output with your own judgment.
How Cash Flow Forecasting With AI Works
Strip away the marketing and the process has four parts:
- Data collection. The tool connects to your bank accounts and accounting software and pulls in transaction history, open invoices and scheduled bills.
- Categorization. It sorts each transaction into a type: payroll, rent, a specific customer's payments, card fees, tax. This is where many tools first use machine learning, because bank descriptions are messy.
- Pattern learning. Models find what repeats and when. Some are classic time-series methods that track trend and seasonality. Others are machine learning models that weigh many signals at once, such as invoice age, customer history and day of the month.
- Projection. The patterns become a forward view of cash in, cash out and ending balance, usually with a range rather than one number.
What AI Does Well in Cash Flow Forecasting
- Payment timing by customer. If one client pays on day 42 of a 30-day term every time, the model learns that and moves their invoices out in the forecast. A simple spreadsheet assumes everyone pays on time.
- Recurring expenses with varying amounts. Utilities, card fees and software bills that land monthly but never at the same figure.
- Seasonality. Slow and busy months that show up in two or more years of history, even if you never labeled them.
- Anomalies. A vendor charging twice, a regular deposit that didn't arrive, a cost category creeping up. Flagging these early is often worth more than the forecast itself.
- Speed. A forecast that refreshes every day from live bank data, instead of one rebuilt by hand each month.
Where It Falls Short
- Thin history. A business with a few months of transactions doesn't give a model much to learn from. Seasonality needs at least a year, ideally two.
- Things that haven't happened before. A new client, a price increase, a planned hire, a loan, a one-off equipment purchase. None of these are in your past data.
- Messy books. Miscategorized or missing transactions train the model on the wrong patterns.
- False precision. A forecast shown as one exact number can feel more certain than it is. Look for tools that show a range or let you run scenarios.
AI Forecasting vs a Traditional Spreadsheet Forecast
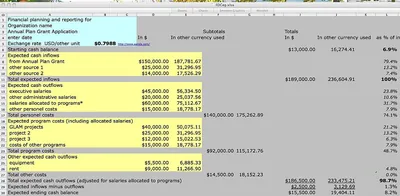
| Spreadsheet forecast | AI forecasting tool | |
|---|---|---|
| Setup | You build it | Connect bank and accounting software |
| Updates | Manual, usually weekly or monthly | Automatic, often daily |
| Customer payment timing | Assumes due dates unless you adjust | Learns actual payment behavior |
| Known future events | Easy to add | Must be added as manual entries or scenarios |
| Needs history | No | Yes, ideally 12 months or more |
| Cost | Free | Monthly subscription |
A Worked Example
A design studio has $40,000 in open invoices due this month. A spreadsheet forecast books all $40,000 as cash in by the due dates. An AI tool looks at history: two clients worth $15,000 usually pay about three weeks late, and the rest pay on time. Its forecast shows $25,000 arriving this month and $15,000 next month. If payroll is $30,000, the spreadsheet says you're fine. The AI forecast shows a $5,000 gap you can plan for now, by chasing the late payers early, delaying a purchase or drawing on a line of credit.
How to Check If an AI Forecast Is Accurate
Compare the forecast with what actually happened. Each week, note the balance the tool predicted four weeks earlier and the real balance. If the gap shrinks over a few months, the model is learning. If it stays wide, check your categorization first, because bad data is the most common cause. Many tools report an accuracy figure; ask how it's measured and over what time horizon.
Is AI Cash Flow Forecasting Worth It for a Small Business?
It's worth trying when you have at least 12 months of history, several customers with uneven payment habits, and cash tight enough that a two-week warning matters. It's less useful for a business with a handful of transactions a month or one dominant customer, where a 13-week spreadsheet forecast does the job in an hour a week. Many accounting platforms now include basic forecasting, so check what you already pay for before adding a separate tool.
Getting Started
- Clean up categorization in your accounting software for the last 12 months.
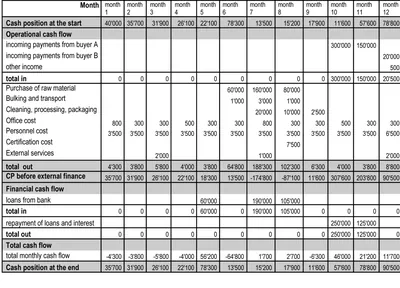
- Build a simple 13-week forecast by hand once, so you know what the numbers should look like.
- Trial a tool, connect your accounts and compare its forecast with yours for four to six weeks.
- Add known future events as scenarios: new hires, contracts, loan payments, tax dates.
For the features that matter more than the AI label, such as bank connectivity, scenario modeling and receivables integration, see what cash flow forecasting software should have. For the habits that make any forecast more useful, see how to spot cash flow gaps early.
Frequently Asked Questions
What is AI cash flow forecasting?
Software that uses machine learning to predict future cash balances from your past transactions. It learns recurring payments, customer payment timing and seasonality, then projects them forward.
How accurate is AI cash flow forecasting?
It depends mostly on your data. With 12 months or more of clean, well-categorized history, AI tools usually beat a forecast that assumes everyone pays on time. With thin or messy data, they can be worse. Track the forecast against actual balances for a few months to find out.
Do I need AI to forecast cash flow?
No. A 13-week spreadsheet forecast works well for most small businesses. AI tools save time and catch payment-timing patterns, which matters more as transaction volume and customer count grow.
What data does AI cash flow forecasting use?
Bank transactions, open invoices and bills from your accounting software, and sometimes payroll and card data. Anything not in those systems, like a new contract or a planned hire, has to be added by you.
Can ChatGPT or another AI assistant forecast my cash flow?
A general AI assistant can help you build or check a spreadsheet forecast from data you give it, but it doesn't connect to your bank or learn from your history over time. Check every formula and number it produces.