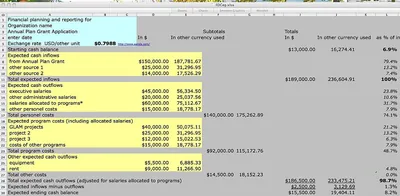
A first budget fails for one reason more than any other: it's built on what you think you spend instead of what you actually spend. Start with real numbers from last month, give every dollar a category, and plan for one bad surprise. That's the whole method. The rest is practice.
Step 1: Find Your Real Monthly Income
Use take-home pay, the amount that lands in your account after tax, retirement contributions and insurance come out. If you're paid every two weeks, multiply one paycheck by 26 and divide by 12, since some months have three paydays. If your income changes month to month, use your lowest normal month and treat anything above it as a bonus. Budgeting with irregular income covers this in detail.
Step 2: Pull Last Month's Spending
Download last month's bank and credit card statements. Put every transaction into one of a handful of groups:
- Fixed bills: rent or mortgage, insurance, phone, loan payments
- Variable needs: groceries, fuel, utilities
- Wants: eating out, shopping, entertainment, subscriptions
- Savings and extra debt payments
This step is where most people get a surprise. Small, frequent purchases (coffee, delivery, app subscriptions) add up faster than anyone expects.
Step 3: Add the Costs That Don't Come Every Month
Look back over the past year for annual and irregular costs: car registration, insurance premiums, gifts, school fees, repairs. Add them up and divide by 12. That monthly amount goes in your budget even though you won't pay it this month. Holding it in a sinking fund keeps it from turning into a credit card balance later.
Step 4: Write the Plan
Now decide where next month's money goes. Start with fixed bills, then savings, then variable needs, then wants. If the total comes out higher than your income, cut from wants first. If it comes out lower, give the leftover a specific job, such as an emergency fund or extra debt payments. Unassigned money tends to vanish.
Worked Example
| Category | Last month (actual) | Next month (plan) |
|---|---|---|
| Take-home pay | $3,400 | $3,400 |
| Rent | $1,250 | $1,250 |
| Utilities and phone | $210 | $210 |
| Car payment and insurance | $430 | $430 |
| Groceries | $520 | $480 |
| Eating out and delivery | $390 | $220 |
| Subscriptions | $95 | $45 |
| Fuel | $170 | $170 |
| Shopping and other | $335 | $195 |
| Irregular costs (averaged) | $0 | $150 |
| Emergency fund | $0 | $250 |
| Total out | $3,400 | $3,400 |
Last month every dollar got spent, but none of it was planned, and nothing went to savings. The plan uses the same income. It trims eating out, unused subscriptions and impulse shopping by $400, then puts $150 toward irregular costs and $250 into an emergency fund.
Step 5: Check In Weekly for the First Month
Spend ten minutes each week comparing spending to the plan. You'll get some categories wrong. That's normal. Move money between categories when you need to, and adjust next month's numbers based on what really happened. Most people need two or three months before a budget feels accurate.
Pick a Method That Fits You
The steps above work with any budgeting style. If you want something simple, the 50/30/20 rule sets three broad targets. If you want more control, a zero-based budget plans every dollar. If you overspend with cards, the envelope method puts a hard limit on each category. And if you'd rather not use a spreadsheet, see the best budgeting apps.
Before you start, run your numbers through the Cash Flow Calculator. It shows in a minute whether you have money left over each month or are running short.
Frequently Asked Questions
How long does it take to set up a first budget?
About an hour to sort one month of statements and write the plan, then ten minutes a week to check in. After two or three months, most people spend less than an hour a month on it.
What if my spending is already more than my income?
Then the budget has done its first job by showing you. Cut wants first, then look at the largest fixed costs, such as housing, car or phone plans. If the gap is still there, the answer is more income or a smaller fixed cost, not more trimming. How to stop living paycheck to paycheck walks through the order.
Should I pay off debt or save first?
Build a small emergency buffer first, often $500 to $1,000, so a surprise bill doesn't go back on a card. Then put extra money toward high-interest debt. The Debt Payoff Calculator shows how much faster extra payments get you there.