In a zero-based budget, income minus every planned expense, savings transfer and debt payment equals zero. It doesn't mean spending everything. It means every dollar has a job before the month begins, including the dollars meant for savings. The short answer explains the idea. This guide shows how to build one.
What You Need Before You Start
- Next month's expected take-home income, from pay stubs or your bank account
- Last month's bank and card statements, to see real spending
- A list of bills and their due dates
- Any annual costs coming up in the next year
Step 1: Write Down Next Month's Income
Use only income you're confident will arrive. Commissions, bonuses and tax refunds don't count until they land. If your pay varies, plan from your lowest normal month.
Step 2: List Every Expense in Priority Order
Go in this order, so the essentials are funded first:
- Housing and utilities
- Food and transport to work
- Insurance and minimum debt payments
- Savings: emergency fund first, then sinking funds, then retirement
- Extra debt payments
- Everything else: eating out, hobbies, shopping, personal spending
Step 3: Assign Amounts Until You Hit Zero
Fill in each category until the total matches your income exactly. If you run out of money before you reach the bottom of the list, the lowest-priority categories get less. If money is left over, give it a job, such as extra savings or extra debt payments.
Worked Example
Monthly take-home pay: $4,100.
| Category | Amount | Running balance |
|---|---|---|
| Rent | $1,400 | $2,700 |
| Utilities and internet | $220 | $2,480 |
| Groceries | $550 | $1,930 |
| Transport | $260 | $1,670 |
| Insurance | $180 | $1,490 |
| Student loan minimum | $240 | $1,250 |
| Emergency fund | $300 | $950 |
| Sinking funds | $200 | $750 |
| Retirement (IRA) | $200 | $550 |
| Extra on credit card | $250 | $300 |
| Personal and eating out | $300 | $0 |
The running balance reaches $0 on the last line. That's the target.
Step 4: Adjust During the Month
Something will go over. When groceries run $60 high, move $60 out of another category, often personal spending. The total stays at zero, and you decide what gives instead of finding out at the end of the month. This is the biggest difference from looser methods like the 50/30/20 rule.
Step 5: Rebuild It Each Month
Each month is different: three paychecks instead of two, a birthday, a car service. Take 30 to 60 minutes before the month starts to copy last month's plan and change what's different. After a few months it gets quick.
Zero-Based Budgeting With Irregular Income
If your income changes, budget only the money you already have. One common approach is to live on last month's income: this month's earnings go into a holding account, and next month's budget is built from that known total. It takes a month or two of saving to get one month ahead, but after that the budget never depends on a guess. See budgeting with irregular income for the full setup.
Common Mistakes
- Forgetting irregular costs. If annual bills aren't in a sinking fund line, they'll break the budget the month they arrive.
- No personal spending line. A budget with zero fun money rarely lasts. Give yourself a set amount with no questions asked.
- Budgeting gross pay. Use the amount that actually reaches your account.
- Giving up after one bad month. The first few months are calibration. The numbers get more accurate each time.
Want to check your starting point first? The Cash Flow Calculator shows your monthly surplus or shortfall in about a minute.
Frequently Asked Questions
Does zero-based mean I have zero dollars in my account?
No. It means zero dollars are unassigned on paper. Money set aside for savings, sinking funds and next week's bills is still in your accounts. It just has a job.
Is zero-based budgeting the same as the envelope method?
They share the same idea, giving every dollar a job. The envelope method adds a hard spending limit by putting each category's money in its own envelope, cash or digital.
Can I do it in a spreadsheet?
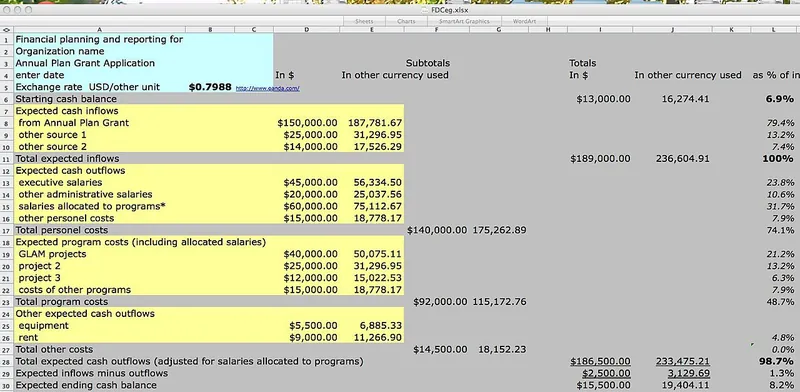
Yes. Three columns are enough: category, planned amount and running balance. Some budgeting apps are built around this method if you'd rather not maintain a sheet.